CollPlant Biotechnologies is not a household name yet, but the Israeli biotech is quietly assembling one of the more audacious pipelines in regenerative medicine — using tobacco plants engineered to produce human collagen as the raw material for 3D-printed implants and tissue scaffolds. According to PR Newswire results, the company reported its second-quarter 2026 financial results this week, revealing a cash and short-term deposit position of approximately $14.5 million as of June 30, 2026 — a figure management says is sufficient to fund operations into the foreseeable future. For a clinical-stage company burning cash while chasing regulatory milestones, that runway matters enormously. This kind of deep-science biotech story sits at an interesting intersection with broader trends in lab-grown tissue models that are already challenging conventional approaches to medical device development.
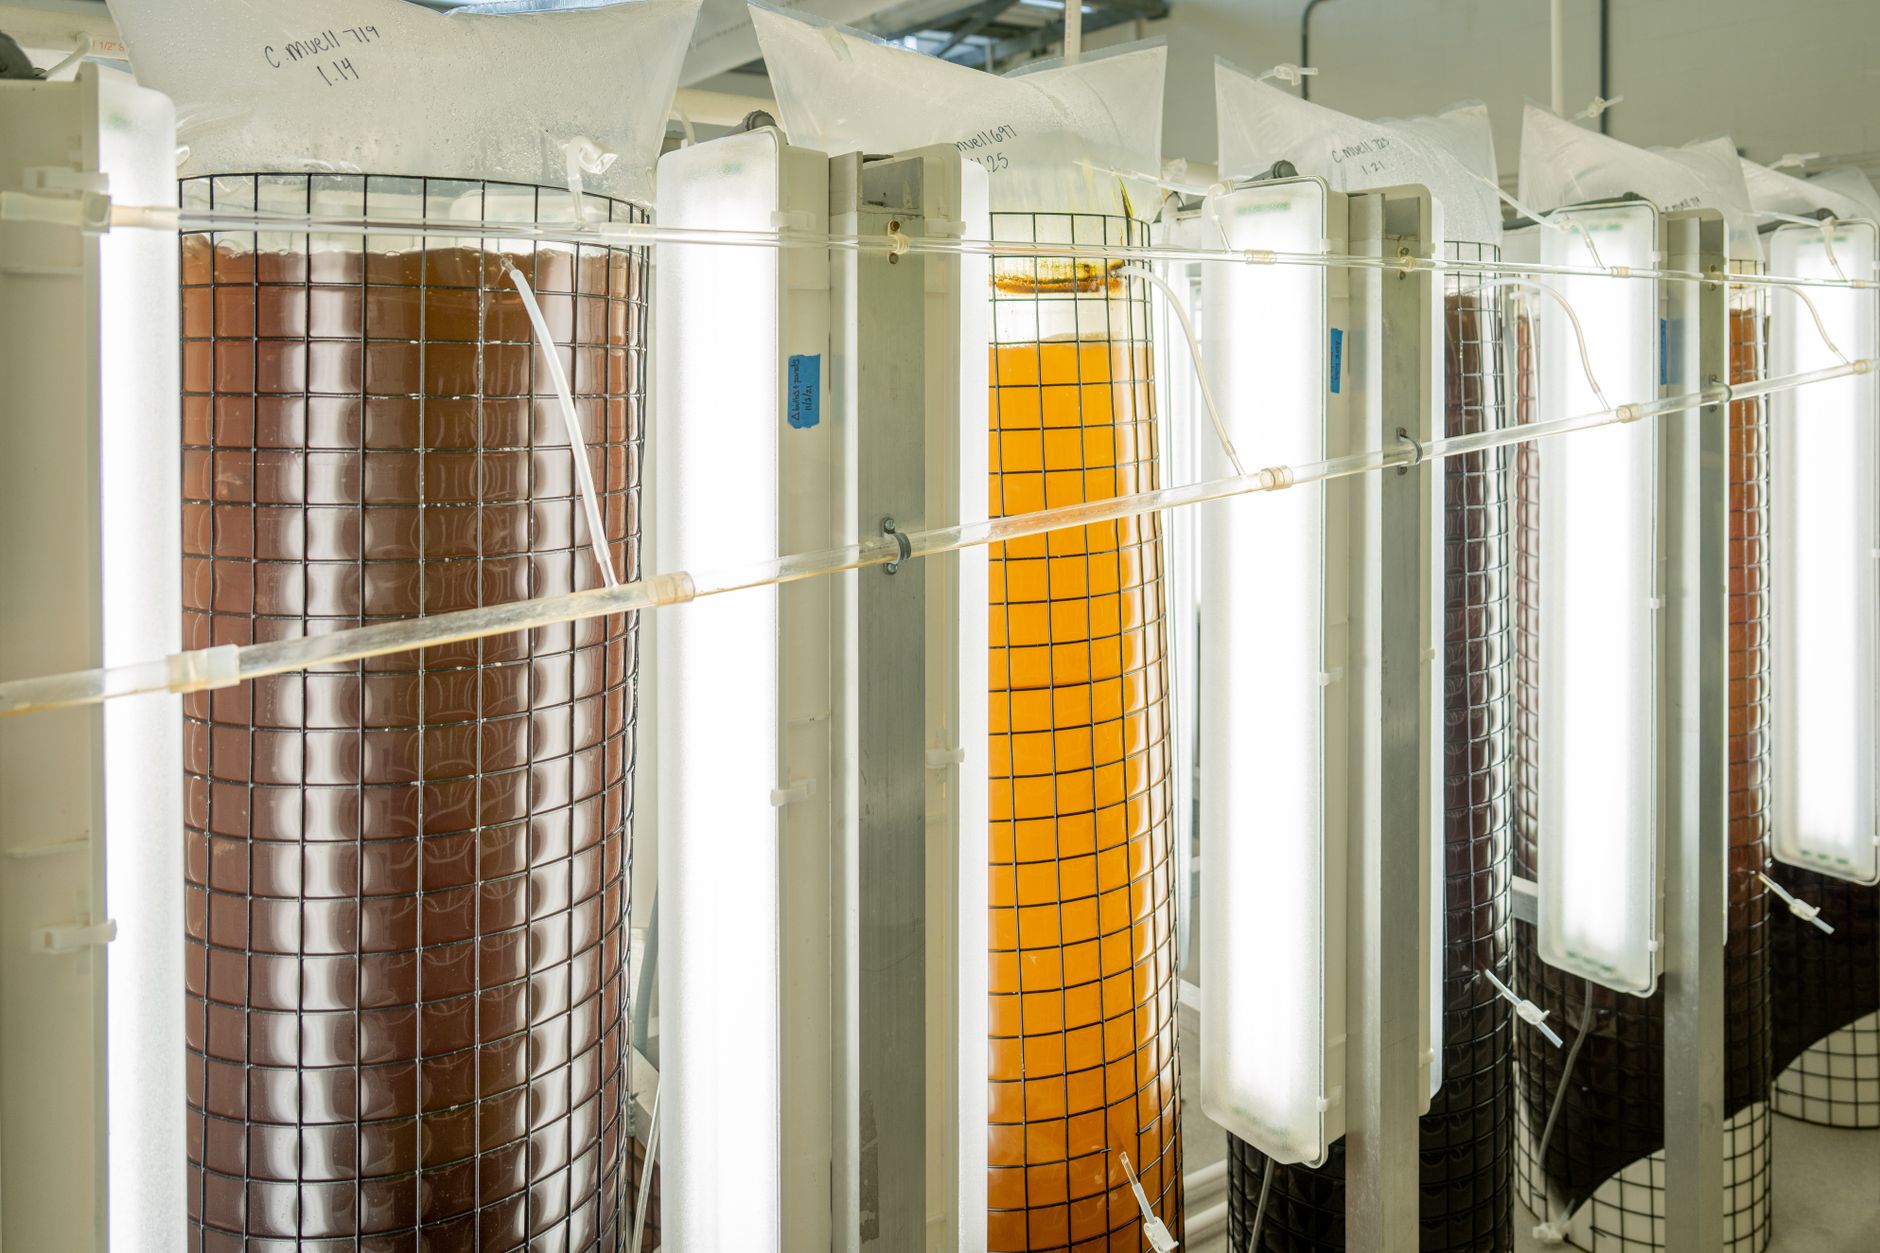
Revenue for the second quarter came in at approximately $1.0 million, consistent with the company’s earlier quarters as it continues to operate primarily in development and licensing mode rather than commercial product sales. Net loss for Q2 2026 was approximately $3.8 million, slightly improved compared to prior-year periods as the company manages its cost base. Research and development expenses remain the dominant line item, reflecting CollPlant’s heavy investment in advancing its rhCollagen-based platform — a plant-derived recombinant human collagen that the company argues outperforms animal-sourced alternatives in purity and consistency.
Breast Implant Program Is the Real Headline
The most consequential update in this earnings cycle has nothing to do with the income statement. CollPlant’s 3D-bioprinted breast implant program, developed in collaboration with AbbVie, remains the company’s highest-profile bet. The program targets the roughly $2 billion global breast implant market with a bioprinted alternative designed to integrate with the body rather than sit inert inside it. CollPlant confirmed that development work on this program is progressing, with ongoing preclinical activities continuing as planned. No specific timeline for an Investigational Device Exemption filing was disclosed in this update, but management signaled confidence in the trajectory.
Beyond breast reconstruction, CollPlant is also advancing its BioInk product line — its rhCollagen-based material sold to research institutions and bioprinting companies for use in developing their own tissue constructs. This segment provides a modest but strategically valuable commercial presence, keeping the company engaged with the broader bioprinting ecosystem while its proprietary implant programs mature. The BioInk business also serves as a proof-of-concept layer: demonstrating that rhCollagen performs at scale before it goes into a human body as a permanent implant.
What the Burn Rate Tells You About the Bet CollPlant Is Making
At roughly $3.8 million in net losses per quarter and $14.5 million in the bank, CollPlant has somewhere between three and four quarters of runway at current burn — unless it raises additional capital, generates licensing revenue, or accelerates collaboration payments. That math is tight, and investors will be watching for any announcements around non-dilutive funding or expanded partnership terms, particularly from AbbVie. The collaboration with one of the world’s largest pharmaceutical companies offers more than just co-development credibility; it represents a potential source of milestone payments that could extend the runway meaningfully.
CollPlant’s story is a long-duration play on regenerative medicine maturing fast enough to meet a company’s funding timeline. The tech funding surge of recent months has shown that international capital is still willing to back deep-science Israeli companies — but biotech requires a specific patience that pure software venture rarely demands. CollPlant is betting that plant-made human collagen is not a curiosity but the foundation of a new category of implantable devices. Q2 2026 does not settle that question, but it shows the company still has enough in the tank to keep making the argument.